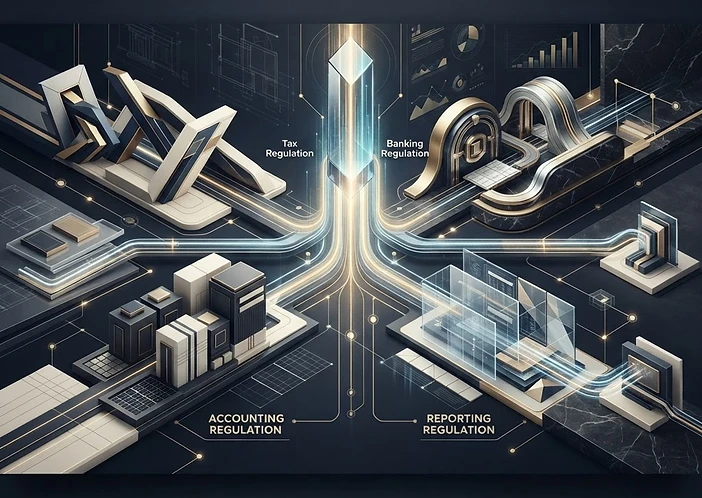
International transactions are often reviewed in silos. The finance team looks at the invoice. Tax looks at withholding. Transfer pricing looks at arm’s length. The bank looks at FEMA documentation. Accounting looks at recognition and foreign exchange.
The transaction, however, is only one transaction. The strongest control is therefore to review it once—across all the rules that may apply.
Begin with the commercial facts
Before analysing a statute, understand what actually happened. Who supplied what to whom? Where was the work performed? Who contracted with the customer or vendor? When did the obligation arise? What currency and payment terms apply? Is the counterparty related?
Clear facts prevent the regulatory analysis from being built around an accounting label that may not describe the underlying transaction.
Income tax and deductibility
The first tax question may be whether income is taxable or expenditure is deductible under domestic law. For cross-border payments, source rules and the nature of the income can become important.
Withholding tax and treaty analysis
A payment to a non-resident can require analysis of Indian withholding provisions and, where applicable, the relevant Double Taxation Avoidance Agreement. Treaty eligibility, beneficial ownership, permanent establishment and characterisation may affect the outcome depending on the facts.
A treaty should not be treated as a lower-rate table. Its application depends on the transaction and the taxpayer.
Transfer pricing
Where the transaction is between associated enterprises and falls within the applicable statutory framework, arm’s-length pricing becomes another layer. Services, financing, guarantees, property, cost allocations and other transactions may fall within the transfer-pricing rules.
The transfer-pricing conclusion should be consistent with the agreement, conduct, invoice and accounting.
FEMA and the banking trail
The same payment may also require classification and documentation under FEMA and the applicable RBI framework. The purpose code, contractual documents, nature of the remittance, ODI/FDI status where relevant and AD-bank requirements should correspond with the commercial substance.
GST and indirect taxes
Cross-border services and supplies can raise GST questions including place of supply, import or export treatment, reverse charge and documentary conditions. These questions are separate from income-tax and transfer-pricing analysis and should not be assumed to follow the same answer.
Accounting and foreign exchange
The transaction must also be recognised correctly in the books: timing, currency translation, receivable/payable classification, taxes withheld, GST treatment and inter-company reconciliation all need to align.
One transaction file is better than six disconnected reviews
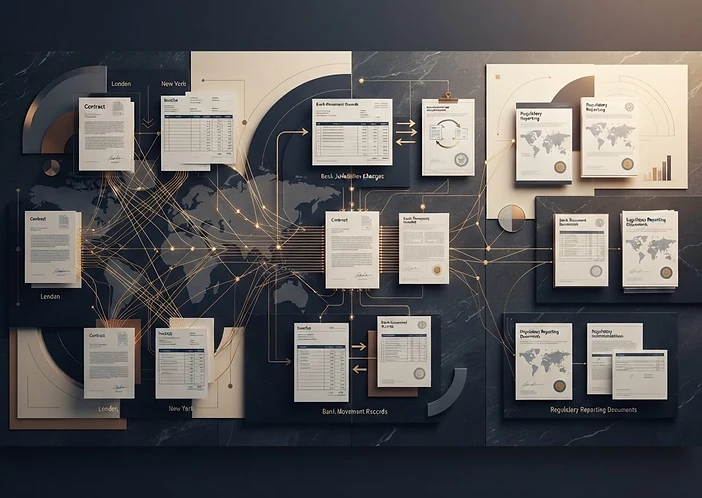
For material cross-border transactions, create a transaction file that contains the agreement, invoice, tax analysis, withholding evidence, transfer-pricing support, FEMA/bank documents, GST position and accounting treatment.
This creates a single audit trail and makes contradictions easier to identify. If the invoice calls a payment 'consultancy', the agreement calls it 'management support', the bank purpose describes something else and the transfer-pricing file uses a fourth description, the inconsistency itself becomes a risk.

Review before payment—not after
Many cross-border errors become difficult to correct after funds have moved. A pre-transaction review can identify withholding, documentation, pricing, regulatory and accounting requirements while there is still time to structure the process correctly.
Build a cross-border transaction matrix
Businesses with recurring international flows should maintain a matrix by transaction type: customer receipts, service fees, management charges, royalties, reimbursements, loans, guarantees, dividends, capital contributions and other material flows.
For each category, the matrix should identify the agreement, tax treatment, withholding, transfer-pricing method, FEMA route, GST position, accounting treatment, reporting obligation and responsible owner.
Perspective
See further
The risk in cross-border transactions often lies not in one rule, but in the gaps between several rules.
At Puneet Puri & Company, we review international transactions across the full chain so that tax, transfer pricing, FEMA, GST, accounting and reporting tell one consistent story.
Official sources
References & regulatory framework
Publication note (18 September 2026): the Income-tax Act, 2025 / Income-tax Rules, 2026 framework applies from 1 April 2026. References to familiar 1961 Act concepts or Form 3CEB are historical/contextual where used; current-year filings should be checked against the applicable 2026 provisions and forms.
Disclaimer: This article is intended for general informational purposes and does not constitute tax, legal, investment or regulatory advice. The application of Indian and overseas laws depends on the facts and circumstances of each transaction and the law applicable at the relevant time.